
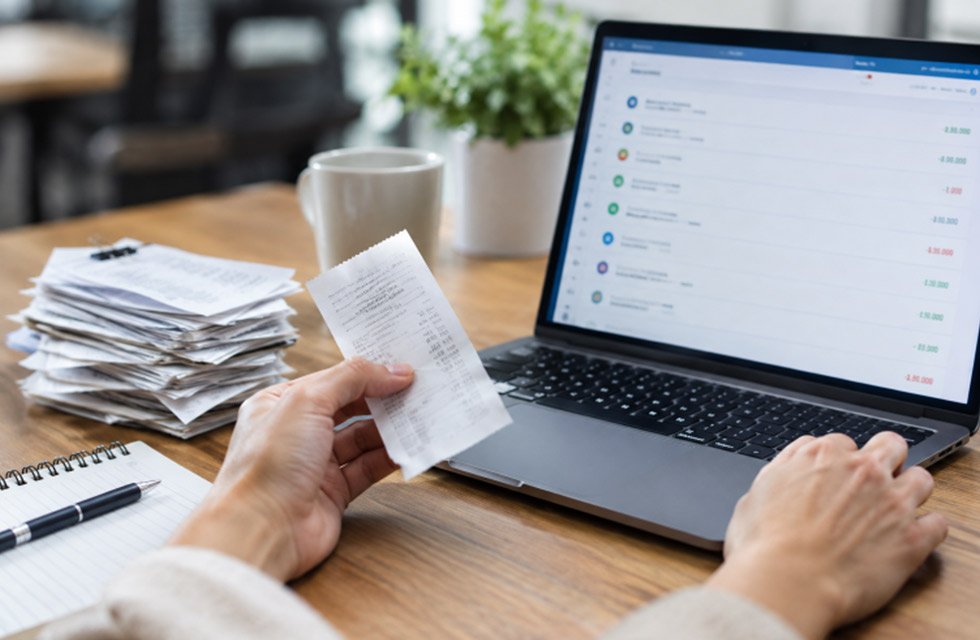
A business bank account should do more than store incoming payments. The right setup helps an owner see available cash, pay bills on time, keep records organized, and protect access to company funds. When comparing business checking options and other digital banking tools, start by considering how money actually moves through the business each week. There is no single best choice for every company. A freelance designer who invoices a few clients each month may value simple transfers and tax set-asides. At the same time, a contractor may need mobile deposits, employee cards, and reliable vendor payments. A clear comparison process keeps feature lists from distracting owners from their real cash-flow needs.
Why Business Banking Needs A Clear Plan
Banking affects more than the account balance. It shapes bookkeeping, tax preparation, customer collections, vendor payments, and decisions about whether there is enough cash for the next payroll or inventory order. Start by listing regular deposits, recurring bills, payment methods, cash deposits, and anyone who may need access to the account. Then compare tools against that list. A platform with polished budgeting features may not be a practical fit for a shop that frequently makes cash deposits. Likewise, a branch-focused account may offer little value to a remote service business that sends invoices and pays contractors online.
Separate Business And Personal Money Applying
Using separate accounts makes it easier to identify company income, operating expenses, owner transfers, and tax-related payments. Clean records reduce the time needed to categorize transactions and make financial reviews more straightforward. Requirements and documentation can vary by business structure and location, so owners should review the steps to open a business bank account before applying. A separate account is especially useful when several payments arrive close together. Rather than sorting personal purchases from business activity later, the owner can review the transaction history and quickly understand what the business earned and spent.
Compare The Total Cost
A low advertised monthly charge does not automatically mean an account costs less. Read the complete fee schedule and estimate costs based on the business’s recent activity. Review the past three months of transactions to identify the most frequently used services.
- Monthly maintenance charges and minimum-balance rules
- ACH, wire, and expedited transfer fees
- Cash deposit and ATM costs
- Outgoing bill-payment charges
- Fees for extra cards, users, or account services
Consider costs alongside time savings. Paying a modest fee for a tool that reduces manual reconciliation may be worthwhile, but only if the business will use that feature consistently.
Look For Cash-Flow Tools
Helpful banking tools make it easier to separate money intended for operations, taxes, payroll, inventory, and reserves. Look for clear transaction views, scheduled payments, automatic transfers, and alerts for low balances, large withdrawals, deposits, or unusual activity.
A simple weekly cash-flow routine can turn those features into a useful habit:
- Review the current available balance.
- List bills due during the next seven days.
- Check expected customer payments and their timing.
- Move money designated for taxes or reserves.
- Update a short cash forecast before committing to new spending.
Check Payment And Transfer Options
Businesses should confirm that an account supports the methods they use to collect and send money. Common needs include ACH transfers for recurring payments, wires for larger or time-sensitive transactions, mobile check deposits, online bill pay, employee debit cards with limits, invoice or payment-link tools, and international payment support when applicable. Transfer speed, daily limits, cutoff times, and fees can vary by provider and payment type. Review those details before relying on an account for payroll, rent, tax payments, or a major supplier order.
Review Security And Deposit Protection
Security controls deserve the same attention as fees. Favor tools that offer multifactor authentication, account alerts, card locks, permission settings, and approval workflows. Give employees and accountants their own access rather than sharing an owner password, and provide only the permissions each person needs. Also, confirm how funds are held and protected. The type of deposit account and ownership arrangement can affect the FDIC insurance coverage applicable, so businesses with substantial balances should verify coverage directly rather than assuming every product receives the same protection.
Match Tools To Business Size
For Freelancers And Sole Proprietors
Prioritize low complexity, mobile access, straightforward transfers, and easy connections to bookkeeping software. Tools that help separate tax money from everyday spending can support better planning.
For Small Teams
Focus on employee cards, spending limits, separate user logins, and approval steps. The goal is to delegate routine purchases without giving every team member unrestricted access.
For Growing Companies
Review higher transaction capacity, payroll workflows, multiple-account options, payment approvals, accounting integrations, and reserve management. Choose a provider that can support added controls without forcing an immediate migration as activity increases.
Avoid Common Selection Mistakes
- Choosing based only on a promotional offer or a monthly fee.
- Ignoring cash deposit needs, transfer limits, or processing times.
- Assuming every digital financial platform is itself a bank.
- Skipping the full fee schedule.
- Giving all team members complete account access.
- Overlooking accounting software compatibility.
Use A Simple Comparison Checklist
Rate each option from one to five for monthly and transaction costs, mobile usability, cash access, payment methods, accounting integrations, employee controls, fraud-prevention tools, deposit insurance clarity, customer support, and room to grow. Give the most weight to functions used every week. A cash-heavy retailer may prioritize access to deposits, while an online consultant may prioritize automation and bookkeeping integrations.
Final Thoughts
The best digital banking setup is not necessarily the one with the longest feature list or the most advanced tools. It is the one that makes business money easier to track, transfer, protect, and plan around daily needs. A suitable setup should support regular payments, help maintain organized records, and provide a clear view of available funds and upcoming obligations. As the business grows, its financial needs and transaction patterns may change, making it important to review whether the current account still meets those needs. Revisit the account every six to twelve months, especially after hiring employees, introducing new payment methods, expanding services, or changing how customers pay. Regular reviews can help identify missing features, unnecessary costs, and opportunities to improve financial management.
